STRONG CASH GENERATION
Ferretti Group
FERRETTI SPA APPROVES THE CONSOLIDATED FINANCIAL RESULTS AS OF 30 JUNE 2026
STRONG CASH GENERATION WITH NET FINANCIAL POSITION OF €95
MILLION (NET CASH), UP €77 MILLION AFTER DIVIDEND PAYMENT
The Board of Directors of Ferretti S.p.A. reviewed and approved the Half-Year Financial Report as of 30 June 2026.
Mr. Stassi Anastassov, the Group’s Global Chief Executive Officer, stated: “My first two months at Ferretti Group have been dedicated to listening, learning and understanding the business from the inside. I have spent time in our shipyards with our employees, dealers, agents and owners, and reviewed our performance brand by brand and market by market.
The conclusion is clear. Ferretti remains an exceptional company with outstanding brands, talented people and one of the strongest balance sheets in our industry. At the same time, the first half confirms that we are operating in a more challenging market than we have experienced in recent years. Customer decision cycles have lengthened, competition has intensified in several segments and order intake remains below the levels required to replenish our backlog at the pace we would like.
Our challenge today is therefore primarily commercial rather than financial. The Company continues to generate healthy cash, maintains a solid financial position and benefits from excellent operational capabilities. Our priority is to rebuild commercial momentum while protecting the quality of our order book, our pricing discipline and the long-term value of our brands.
Over the past two months we have already launched a number of initiatives to strengthen commercial execution, improve owner experience, reinforce product governance and increase organizational accountability. These actions are not designed simply to improve the second half of 2026. They are intended to position Ferretti Group for stronger and more sustainable growth in 2027 and beyond.
The market environment remains uncertain, and we expect that uncertainty to continue. Our focus is therefore not on chasing short-term volume, but on making the right decisions for our customers, our shareholders and the long-term strength of our Company. I am confident that this disciplined approach will create greater value over time”
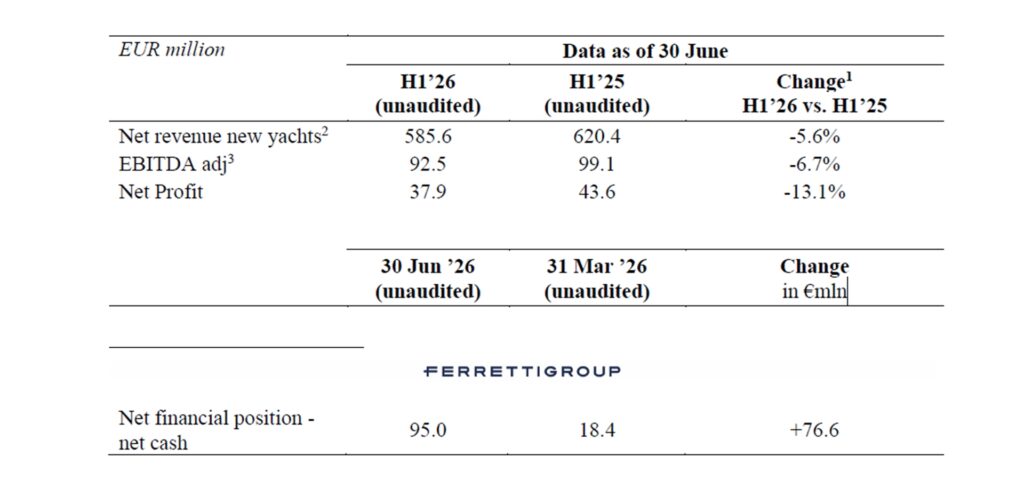
The consolidated key financial highlights of the first semester 2026 as follow:
1.Sums might not add up to total due to rounding
2 Revenue without pre-owned business
3 Excluding non-recurring costs and other minor non-recurring events
The Executive Officer for Financial Reporting, Marco Zammarchi, declares in accordance with
Article 154 bis, paragraph 2, of the Consolidated Finance Act, that the accounting information
contained in this press release corresponds to the underlying accounting documents, records and
accounting entries.
NON-IFRS MEASURE
To supplement the Group’s consolidated results which are presented in accordance with IFRS,
EBITDA, adjusted EBITDA, adjusted EBITDA/net revenue without pre-owned, being non-IFRS
measures, were also presented. The Group is of the view that this measure facilitates comparison
of operating performance from period to period by eliminating potential impacts of certain items
and believes that this measure provides useful information to understand and evaluate the
Group’s consolidated income statements in the same manner as they help the Group’s
management. However, the Group’s presentation of EBITDA may not be comparable to similar
terms used by other companies. The use of this measure has limitations as an analytical tool, as
such, it should not be considered in isolation from, or as substitute for analysis of, the Group’s
results of operations or financial condition as reported under IFRS.
The periodic financial information, as of 30 June 2026, has not been audited by the Company’s
independent auditing firm.
The Company defines (i) EBITDA as profit after tax plus financial expenses (including the result
of operating foreign exchange conversion but excluding exchange rate gains/(losses) related to
financial transactions), depreciation and amortization, and income tax expense, and less financial
income and income tax benefit; (ii) adjusted EBITDA as EBITDA adjusted by adding back
certain special items (including non-recurring costs and other minor non-recurring events); and
(iii) net revenue without pre-owned as net revenue excluding revenue generated from the trading
of pre-owned yachts.
Net revenue from new yachts amounted to €585.6 million, down 5.6% year-on-year;
however, reflecting an improved trend in the second quarter of 2026, with revenue
declining by 2.9% in Q2’26 vs. Q2’25, compared with the decline of 8.0% in Q1’26
vs. Q1’25
- Adjusted EBITDA reached €92.5 million with a margin of 15.8%, confirming the
resilience of the Group’s profitability profile - Net profit remains robust at €37.9 million, compared with €43.6 million reported in
the first half of 2025 - Order intake totaled €341.4 million in the first half of 2026, down versus the sound
comparative period in the first half of 2025, when it reached €467.3 million - Net backlog stood at €564.9 million as of 30 June 2026, compared with €760.8 million
at the end of the first semester 2025 - The Group reported a net financial position (net cash) of €95.0 million as of 30 June
2026, an increase of €76.6 million compared with 31 March 2026, supported by the
seasonal release of net working capital associated with deliveries and after
distributing approximately €37.2 million in dividends - Full-year guidance updated on a prudent basis in light of the continued geopolitical
uncertainty, particularly in the Middle East, and the broader macroeconomic
environment that continue to lengthen negotiation processes